The word does all of this work at once:
- Rule systems. A person wrote the logic. Inspectable, and older than the term by decades.
- Predictive models. Score or classify something that already exists: credit risk, fraud, demand, machine failure.
- Perception systems. Decide what an image, a recording, or a document is.
- Generative models. Produce new text, code, images, or audio from patterns learned in training.
- Agents. Act on a standing authorization, with nobody waiting on the other end.
- Assemblies of several of the above, which is what nearly every real product turns out to be.
Arguing about which one deserves the name gains nothing. What matters is that a requirement like "explainability" or "human oversight" means completely different work depending on which is in front of you. Most deployed systems are the sixth kind, so a rule usually lands on several at once.
Three distinctions do the sorting
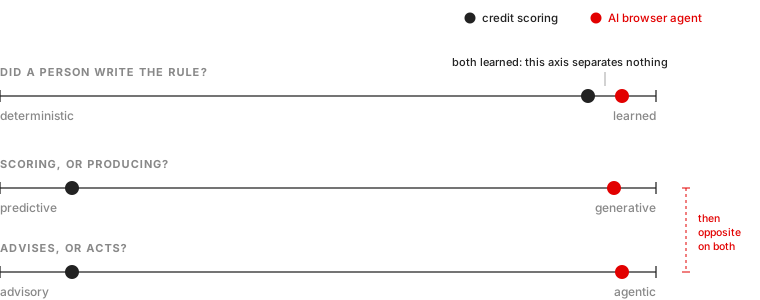
- Rule-based or learned. Did a person write the rule, or did a machine find the pattern? This decides whether the logic can be audited at all.
- Predictive or generative. Is it scoring something that exists, or producing something new? The risk, cost, and infrastructure profiles are close to opposite.
- Advisory or agentic. Does it recommend to a person, or act on its own? This is where liability changes character.
They are independent. A system sits somewhere on each, and its position on one predicts nothing about the next.
Why one label fails
A credit model is learned, predictive, and advisory. A browser agent is learned, generative, and agentic. They have different failure modes, different infrastructure, and different bodies of existing law already covering them. A rule written for one reaches every system that shares an axis with it: write for the agent and you also reach the credit model, which has been regulated for decades; write for the credit model and the agent walks through the gap.
Inside an organization the same thing happens with AI policy. "Approved AI tools" lumps together a fraud model, a writing assistant, and an agent with access to the finance system. Sorting them on the three axes first tells you which rules each one actually needs.
Sentinel, an AI gateway, is a practical example of a control that does not depend on the kind of system. It covers coding agents such as Claude Code and apps and agents built on any framework, with no application code to change.
Frequently asked questions
- What are the main kinds of AI?
- Six: rule systems, where a person wrote the logic; predictive models, which score or classify something that exists; perception systems; generative models, which produce new text, code, images, or audio; agents, which act on a standing authorization; and assemblies of several of these. Nearly every real product turns out to be an assembly.
- What three questions sort AI systems?
- Did a person write the rule or did a machine learn it, does it score something or produce something, and does it advise a person or act on its own. The three are independent, so a system sits somewhere on each, and its position on one predicts nothing about the next.
- Why does one label for all of these cause problems?
- A credit model is learned, predictive, and advisory, while a browser agent is learned, generative, and agentic. They have different failure modes, infrastructure, and existing law. A rule written for one reaches every system that shares an axis with it, so a rule written for the agent also reaches the credit model, which has been regulated for decades.
- Why does a requirement like explainability mean different things for different AI?
- A requirement such as explainability or human oversight means completely different work depending on which kind of system is in front of you. Most deployed systems are assemblies, so a single rule usually lands on several kinds at once. Sorting each system first tells you which rules it actually needs.
- How should an organization use these distinctions in its AI policy?
- Sort the tools before writing the rules. An approved AI tools list can lump together a fraud model, a writing assistant, and an agent with access to the finance system. Placing each one on the three axes first shows which rules each one actually needs, and which existing law already covers it.